
Clari5 FRAML
Unified real-time fraud, risk & AML compliance
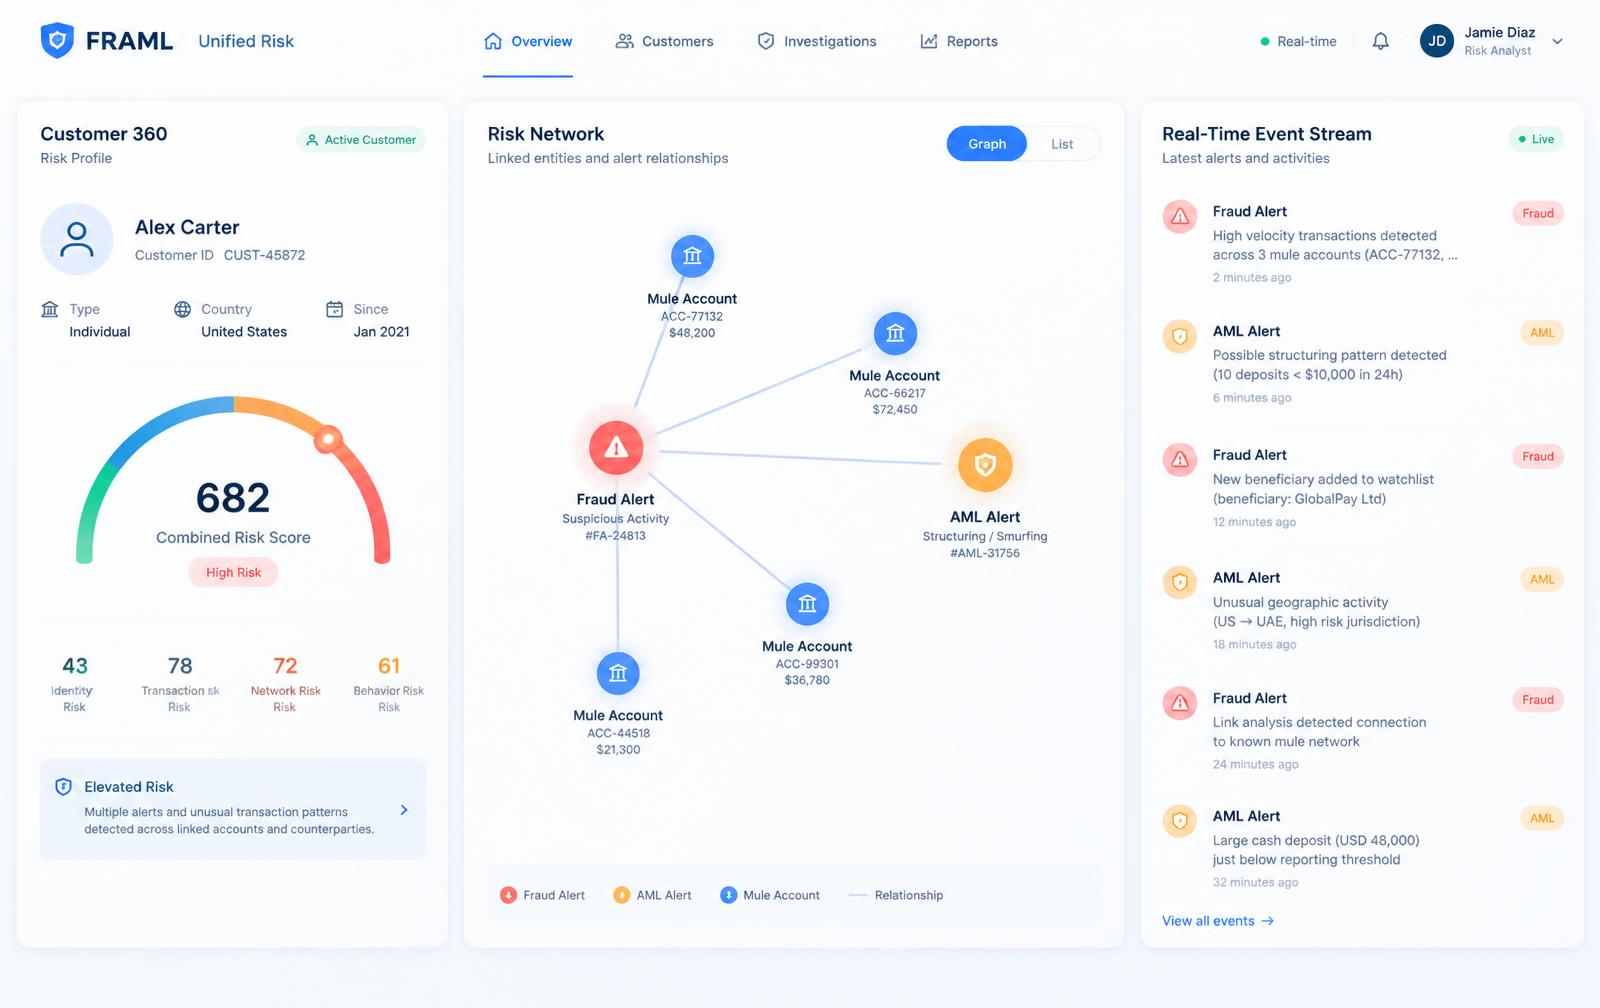
One platform that shares data, systems, intelligence and teams to produce a single holistic view of financial crime risk. A single suspicious event triggers both fraud and AML scrutiny — in real time, across every channel.
Cumulative fraud losses
projected 2023–2028 · Juniper Research
Global AML penalties
full-year 2024 · Fenergo
AML fines in H1 2024
up 31% year-over-year · Fenergo
Real-time payments
of global e-payments by 2027 · ACI / GlobalData
The structural gap
Siloed controls in a real-time world.
Every mule account, every laundering network, begins with a fraud event that a siloed system saw and closed in isolation. Most institutions have fraud and AML monitoring — but on separate data, systems and teams, with no unified risk verdict.
With losses compounding and enforcement intensifying, the question is no longer whether to converge fraud and AML — but how fast.
What is FRAML?
Individual checks have blind spots. Correlated intelligence does not.
Fraud is a predicate offense to money laundering. Clari5 FRAML correlates events across the full criminal lifecycle in real time — not as an integration layer, but as one platform on one data model.
-
1
Fraud committed
- Account takeover (ATO)
- APP scams
- Identity theft
-
2
Illicit proceeds generated
- Mule networks
- Synthetic identities
-
3
Money laundered
- Structuring
- Layering
- Cross-border flows
The transformation
From fragmented to unified.
What changes when an institution moves from a siloed operating model to converged FRAML.
Data
Separate stores; no shared customer view
Detection
Channel-siloed, batch-mode processing
Investigation
Duplicate case management by separate teams
Reporting
Separate STR/CTR; manual, error-prone
Cost
Dual tech stacks, duplicate staffing
Data
Unified data lake with 360° risk profile
Detection
Real-time, cross-channel; one event triggers both
Investigation
Joint case management with shared context
Reporting
Consolidated regulatory reporting + goAML
Cost
Single platform, consolidated infrastructure
Approaches to FRAML
Build, buy or integrate? Evaluate your options.
Build in-house
Strengths
Full customization, IP ownership
Trade-offs
18–36 month build cycle; ongoing maintenance burden; hard to keep pace with evolving threats
Best fit
Large Tier 1 banks with deep engineering teams
Point solutions + integration layer
Strengths
Best-of-breed per domain, flexibility to swap vendors
Trade-offs
Integration creates new silos; no real-time cross-domain intelligence; multiple vendors
Best fit
Institutions already committed to specific AML/fraud vendors
Unified FRAML platform (Clari5)
Strengths
Single data model from Day 1; real-time cross-domain detection; 12–16 weeks to value
Trade-offs
None
Best fit
Institutions prioritizing speed, real-time capability and total cost
The platform
Four modules. One intelligence layer.
A purpose-built real-time intelligence platform spanning four functional modules, with shared capabilities underneath.
- Consolidated regulatory reporting (STR/CTR/SAR + goAML)
- Unified case management
- Customer 360° risk profile
- SaaS or on-premise deployment
Enterprise Fraud Risk Management
Cross-channel real-time fraud detection
Real-Time AML
Transaction monitoring, CRC, screening
Risk Orchestration
ML models, scenario design, behavioral AI
Mule & Ring Detection
Graph-based link analysis
Business impact
Lower cost. Better detection. Stronger posture.
Cost reduction
Duplicate systems eliminated
Retire parallel stacks, eliminate redundant investigations on the same customers, consolidate vendor contracts and redeploy cross-trained staff.
Detection uplift
Unified customer risk view
One suspicious event triggers both fraud and AML scrutiny. Graph analytics connect mule accounts across products; behavioral anomaly detection spans all transaction types.
Regulatory resilience
Set against 2024 AML penalties
Consolidated SAR/CTR/STR with full audit trails, joint investigation workflows, and one platform aligned to FATF, BSP, MAS and FinCEN.
Engagement model
Three steps to a FRAML business case.
Typical deployment: 16–20 weeks.
Discovery & assessment
Map fraud and AML architecture, identify data gaps, quantify duplication costs — a gap analysis and readiness scorecard.
2–4 weeks
Tailored demonstration
Walkthrough configured for your transaction mix, channels and regulatory context, including fraud scenario simulation.
1–2 weeks
Business case & scoping
Customized implementation roadmap and investment range scoped to your environment.
2–4 weeks
FAQs
Frequently Asked Questions: Clari5 FRAML
FRAML (Fraud Risk and Anti-Money Laundering) connects fraud detection, AML monitoring and investigation through shared intelligence. Instead of treating suspicious activity as separate fraud and AML alerts, Clari5 FRAML helps banks correlate signals across channels, customers, transactions and connected accounts in real time. This gives teams broader context to investigate potential financial crime and act on related risks.
Fraud proceeds can move through mule accounts and connected networks before being layered or transferred elsewhere. Clari5 FRAML combines cross-channel monitoring, customer risk profiles and graph-based link analysis to help identify relationships that individual fraud or AML systems may miss. Connecting these signals gives investigators a more complete view of suspicious activity across accounts and products.
Integration feasibility depends on your existing architecture, data availability, interfaces and processing requirements. Clari5 FRAML is designed to bring fraud and AML intelligence together on a shared platform, with SaaS and on-premise deployment options. A technical assessment should establish how existing systems will connect, which capabilities can be retained, and what changes may be required.
The objective is not simply to generate fewer alerts. It is to help investigators distinguish meaningful risk from activity that requires no further action. Clari5 FRAML combines transaction monitoring, behavioural analysis, machine learning and connected customer intelligence to support risk-based detection and investigation. Actual improvements in false positives, alert quality and investigation time should be validated against your bank's existing performance and control requirements.
No. Technology convergence does not automatically require organisational restructuring. Clari5 FRAML supports shared intelligence and investigation context while banks retain their chosen governance, reporting lines and approval responsibilities. The operating model should define how teams share relevant information, escalate cases, manage sensitive disclosures and maintain clear accountability for fraud decisions and AML obligations.
Clari5 FRAML supports consolidated STR, CTR and SAR reporting, goAML capabilities, unified case management and audit trails. The relevant reporting formats, workflows and controls must be assessed against the requirements of each jurisdiction and financial institution. During evaluation, banks should verify applicable regulatory coverage, evidence retention, access controls, reporting accuracy and the ability to reconstruct investigation decisions.
An in-house build offers control and customisation but requires sustained engineering and maintenance resources. Point solutions may provide specialist capabilities, although integration can leave gaps in shared intelligence and create additional operational overhead. A unified FRAML platform offers a common intelligence layer across fraud and AML. The right choice depends on your existing investments, integration complexity, control requirements, internal expertise and total cost of ownership.
Clari5 FRAML supports SaaS and on-premise deployment. The appropriate approach depends on your infrastructure, data residency obligations, security policies, transaction volumes and integration requirements. Discovery should establish the target architecture, migration approach, dependencies, testing requirements and implementation responsibilities before a delivery timeline is committed.
Implementation time depends on the bank's architecture, data readiness, integration scope, regulatory requirements and testing needs. Clari5's FRAML page describes a structured engagement covering discovery and assessment, a tailored demonstration, and business case development and scoping. Its stated typical deployment timeline is 16–20 weeks, but this should be validated for your institution. A detailed plan should cover parallel testing, performance validation, user acceptance, fallback arrangements and controlled transition to production.
Start by establishing a baseline for fraud losses, alert volumes, false-positive rates, investigation time, reporting effort, technology costs and operational duplication. Then assess the potential value of connected detection, shared investigations and platform consolidation against implementation, integration, licensing and ongoing operating costs. A structured evaluation with Clari5 should agree measurable success criteria, validate capabilities against representative scenarios, and produce a bank-specific roadmap and investment estimate before a purchasing decision.
Explore the Clari5 platform
Enterprise Fraud Risk Management
Real-time, cross-channel fraud detection and in-flight decisioning.
Learn MoreAnti-Money Laundering
Explainable AML monitoring, screening, case management and regulator-ready reporting.
Learn More